Quick Summary
Key Features
- Numberless physical card
- 1.5% FX fee
- SadaBiz USD freelancer payouts
- Zero local fees
Main Advantages
- Free virtual card issuance
- Both virtual and physical card options
Notable Limitations
- Availability limited to a small number of regions
- Terms change often — the provider's live numbers are final
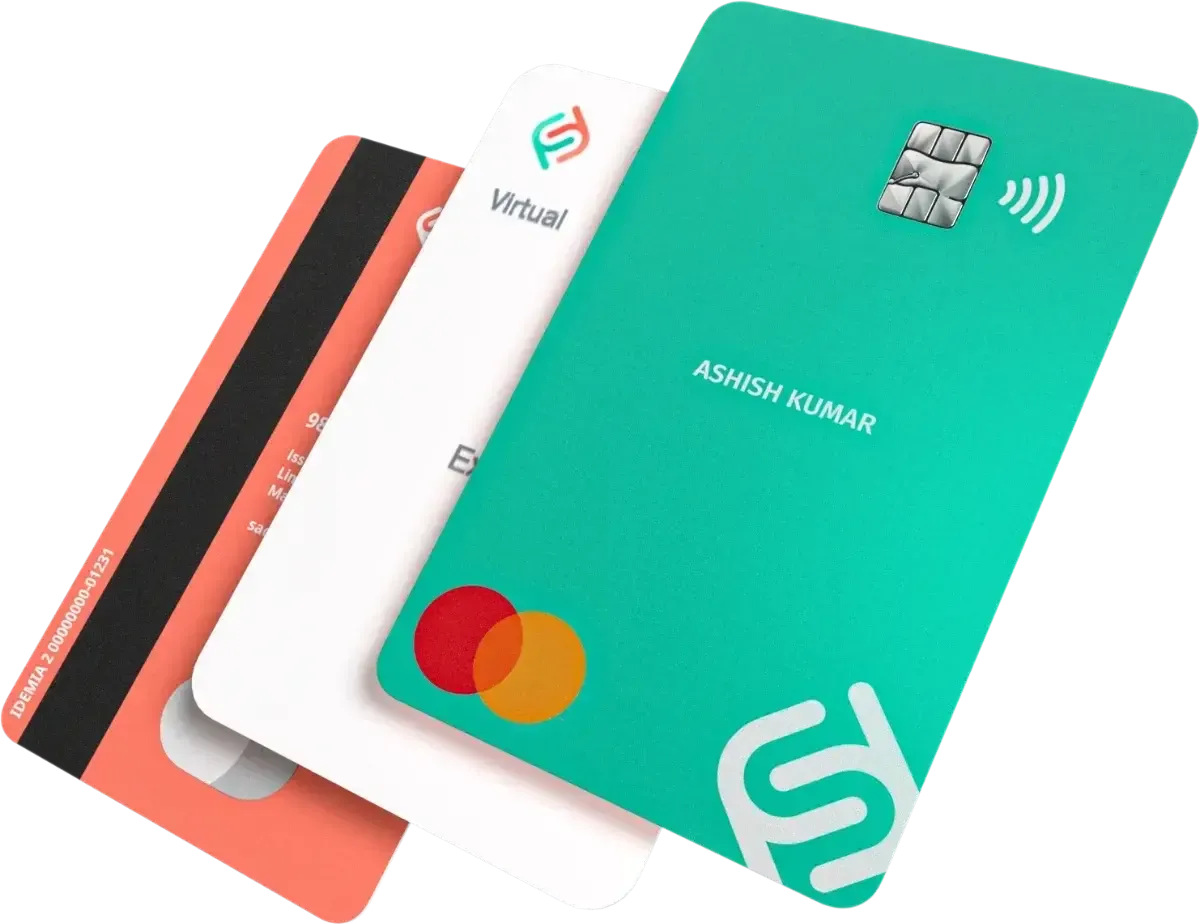
The cards
Every format SadaPay issues — pick the one that fits how you spend.
1Can I get this card?
Supported Countries Map — powered by our availability data.
SadaPay: Reported in 1 country across 1 region (Pakistan).
Coverage reported by the provider — the exact applicant list is confirmed in-app.
2What does it cost?
Every fee we could verify for the SadaPay card.
Fees verified October 13, 2026 from public web sources. Fees change often — always confirm the app's live numbers before signing up. This page is for information only, not financial advice.
| Fee | SadaPay Virtual | SadaPay Physical |
|---|---|---|
| Issuance fee | $0 | $0 |
| Monthly fee | $0 | $0 |
| FX fee | Varies by region — confirm in-app | Varies by region — confirm in-app |
3What do I get?
Perks, rewards and capabilities that come with the card.
| Category | Benefit |
|---|---|
| Card options | Numberless physical card |
| Spending & FX | 1.5% FX fee |
| Perks | SadaBiz USD freelancer payouts |
| Perks | Zero local fees |
4What do they need from me?
What you will have to provide or meet to get and use the card.
| Requirement | What it means |
|---|---|
| Identity check | ID verification required — verify your identity in the app before ordering |
| Funding | You will need a way to load the card: bank transfer, Raast, SadaBiz links |
| Age | You must be 18 or older to apply |
What is SadaPay?
SadaPay is a digital wallet issued under a regional electronic money institution (EMI) license, built around a simple promise: no fees on local spending. The virtual Mastercard is free, domestic transactions carry zero fees, and the app has built a loyal following on the strength of transparent pricing and a clean user experience. For online purchases, the virtual card works anywhere Mastercard is accepted.
SadaPay's distinguishing feature is SadaBiz, a business wallet aimed at freelancers that can receive USD payments from international clients — a direct answer to the region's gig economy. Combined with the free virtual Mastercard, it gives freelancers a path from dollar earnings to online spending without a traditional bank account in the middle.
Card types offered
SadaPay issues a free virtual Mastercard usable immediately for online checkouts, subscriptions, and ad platforms. A physical debit card is available for a one-time issuance fee for in-store spending and ATM withdrawals. Both cards draw from the same wallet balance. The virtual card is the core product — most users never need the physical one unless they want cash access or in-store payments.
Fees explained
Card issuance: the virtual Mastercard is free; the physical card carries a one-time fee. There is no monthly fee, and local transactions are free — this is SadaPay's headline strength and it is genuine. The catch is international spending: foreign-currency card transactions carry a 6% fee, with a small flat fee added on very small transactions. That is steep — a $100 international purchase costs $106, versus about $100.30 on Wise.
The 6% international fee is the single most important number in this review. It makes SadaPay one of the most expensive options on this list for dollar-denominated spending like ads, SaaS, or subscriptions. The product is priced for a user whose spending is overwhelmingly domestic, with the international card as a convenience feature rather than a core use case.
How to get a SadaPay card
- Download the SadaPay app and register with your mobile number.
- Verify your identity with your national ID per the EMI's KYC requirements (diaspora users may register with overseas ID documents where supported).
- Issue your free virtual Mastercard from the cards section — ready for online use immediately.
- Top up via bank transfer or, for freelancers, through SadaBiz receiving.
- Order the physical card optionally for ATMs and in-store payments.
Top-up methods
Standard funding is via local bank transfer, reported free. SadaBiz adds freelancer-focused receiving: USD payments from international clients can land in the business wallet, which is the standout top-up path for the gig economy in its market. In-app transfers between SadaPay users are instant. There is no crypto top-up; all funding flows through domestic banking rails.
Availability
SadaPay is licensed for its home market, with sign-up also extended to diaspora users holding overseas national ID documents. Like other regional EMIs, it is not a global product — registration requires qualifying ID, and the wallet is denominated in the local currency. Within its footprint, onboarding is fully digital and typically quick.
Security and card controls
The app offers instant freeze/unfreeze for the virtual card, biometric login, and real-time transaction notifications. As a licensed EMI, funds are held under regulatory safeguarding rules. Standard hygiene applies: freeze the card when not in use for subscriptions you want to pause, and keep a separate virtual card mindset — SadaPay issues one virtual card per account, so heavy subscription users should be extra careful with the number.
How SadaPay compares on price
For domestic spending, SadaPay is genuinely excellent — zero fees is zero fees, and few wallets anywhere match that. For international spending, it is among the priciest options here: 6% versus ~0.26%+ at Wise, free-within-allowance at Revolut, and even 3–4% at NayaPay. A freelancer receiving $1,000 via SadaBiz and spending it internationally would lose $60 to the card fee alone — routing that spend through a global FX card instead keeps almost all of it. Use SadaPay for what it is priced for (local, fee-free life) and not for what it is not (cheap dollar spending).
Limits and things to watch
The 6% international fee dominates every decision about this card — memorize it before attaching the card to any dollar-billed subscription or ad account. Currency support is single-currency; there are no multi-currency balances, so every foreign transaction converts at payment time. Availability is regional, and the physical card's one-time fee, while small, is worth noting. Finally, SadaBiz receiving is a business-wallet feature with its own terms — read them before routing client income through it.
SadaBiz in detail
SadaBiz deserves a closer look because it is the main reason freelancers choose SadaPay. It is a business wallet that can receive USD payments from international clients — invoicing tools, payment links, and receiving details designed for gig workers who earn in dollars but live on the local currency. Money received through SadaBiz lands in the business wallet, from where it can be moved to the personal wallet for spending with the virtual Mastercard. The receiving side is the value; the spending side is where the 6% international fee bites. Smart users therefore treat SadaBiz as an income rail and route dollar-denominated expenses (ads, SaaS, subscriptions) through a low-FX card, keeping SadaPay for domestic spending where it is genuinely free.
Everyday use: the zero-fee local wallet
Strip away the international card and SadaPay is one of the best-value wallets in its market: no monthly fee, no local transaction fees, instant transfers between users, and a clean app that makes the balance the hero. Groceries, fuel, dining, local e-commerce — all of it costs exactly the sticker price. This is a bigger deal than it sounds: many traditional accounts nickel-and-dime users with SMS charges, minimum-balance penalties, and transfer fees that add up invisibly. SadaPay's transparency is why it has loyal users, and the free virtual Mastercard is a fine tool for domestic online shopping where no forex applies at all.
The 6% rule: when not to use the card
Make the 6% international fee a hard rule in your head: if the merchant bills in a foreign currency, do not use this card. A $50/month SaaS subscription costs $53 on SadaPay versus ~$50.15 on Wise — $34 a year wasted on one subscription. Ad spend is worse: $1,000/month in ads costs $60 in fees, money that buys nothing. The fix is a two-card setup: keep SadaPay as your daily local wallet and put a Wise or Revolut virtual card on every foreign-billed subscription, ad account, and checkout. Check each subscription's billing currency in its settings — some services let you switch to local billing, which would make the charge domestic and fee-free on SadaPay.
One last practical note: SadaPay issues a single virtual card per account, so guard the number carefully — unlike platforms with unlimited free virtual cards, you cannot burn and replace it casually. Use it for trusted merchants and domestic checkouts, and lean on a multi-card platform like Revolut or Mypal for experimental signups and trials.
Who should use SadaPay?
Residents of its home market who want a truly fee-free local wallet with a free virtual Mastercard for occasional online purchases. Freelancers in the region get added value from SadaBiz dollar receiving. Anyone spending significantly in foreign currencies — ads, SaaS, international subscriptions — should use a global FX card for those transactions and keep SadaPay for domestic life.
Pros
- Free virtual Mastercard
- Zero fees on local transactions
- SadaBiz USD receiving for freelancers
- Clean app with instant card controls
- Diaspora sign-up supported
Cons
- Steep 6% fee on international transactions
- Regional availability only
- No multi-currency balances
- Physical card has a one-time issuance fee
Card specs
| Feature | SadaPay |
|---|---|
| Virtual card issuance | $0 |
| Monthly / annual fee | $0 |
| Card network | Mastercard |
| Card type | Virtual + Physical |
| KYC | ID verification required |
| Top-up methods | bank transfer, Raast, SadaBiz links |
| Supported assets | — |
| Regions | Pakistan |
Rating breakdown
Pros & cons
Pros
- Free virtual Mastercard
- Zero fees on local transactions
- SadaBiz USD receiving for freelancers
- Clean app with instant card controls
- Diaspora sign-up supported
Cons
- Steep 6% fee on international transactions
- Regional availability only
- No multi-currency balances
- Physical card has a one-time issuance fee
Frequently asked questions
Is the SadaPay virtual card free?
Yes, the virtual Mastercard is free to issue. The physical card carries a small one-time issuance fee.
What is SadaPay's international transaction fee?
6% on foreign-currency card transactions, plus a small flat fee on very small transactions — among the highest rates on this list.
What is SadaBiz?
SadaBiz is SadaPay's business wallet for freelancers, which can receive USD payments from international clients — useful for gig workers in its home market.
Can I use SadaPay for Facebook ads?
Technically yes — the virtual Mastercard works on ad platforms — but the 6% international fee makes it an expensive choice for ad spend. A low-FX card is far cheaper.
Is SadaPay available internationally?
SadaPay is licensed for its home market, with sign-up extended to diaspora users holding qualifying overseas ID. It is not a global product.
Does SadaPay charge a monthly fee?
No. There is no monthly fee, and local transactions are free.
Our verdict
SadaPay delivers exactly what it promises: a free virtual Mastercard with genuinely zero local fees, plus SadaBiz for freelancer dollar income. But the 6% international fee makes it a poor choice for dollar-denominated spending — the very use case many virtual card shoppers care about. Excellent local wallet; bring a Wise or Revolut card for anything billed in foreign currency.
Get the SadaPay card
Apply directly with the provider — check current fees and availability for your country in their app.
Visit SadaPay's official site →Fees verified October 13, 2026. Always confirm live numbers in-app.